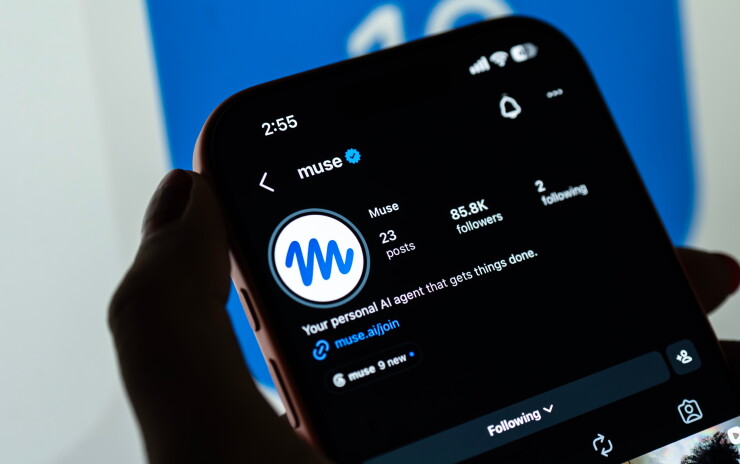
AI agents are arriving in droves. Over the past month, Meta introduced Muse, Instinct launched its assistant and OpenAI introduced ChatGPT Dots. Forward-thinking carriers are welcoming it.
In just over a month, Muse topped 10.9 million downloads since its Sept. 8 launch and reached an estimated 2.5 million daily active users, outperforming ChatGPT's launch. The adoption numbers are staggering and even more transformative: these AI agents are equipped to actually shop for insurance. Naturally, this sparked an immediate industry reaction. Some announced they were blocking the technology entirely, while others embraced the change and created paths.
Historically, shopping for insurance has been time-consuming and complicated. Even digital shoppers had to navigate multiple screen flows and manually enter information to get a quote. Finding the best price and coverage is challenging. The process disincentivized switching carriers, creating a 'loyalty penalty' for staying with your current insurer. Loyalty should save drivers money, but in car insurance, it often doesn't.
Now, shoppers can tap into AI agents to do the work. The agents gather information, coverage options, and quotes from multiple insurance companies based on what shoppers tell them. AI makes a task that would be improbable for a human — quoting with every insurance company possible — simple and automated. Additionally, the AI agent can shop continuously, finding and providing even better options as they become available. Customers can save hundreds, if not thousands, of dollars a year for the exact same coverage. This puts the power in consumers' hands, and the agent becomes their most valuable tool and advocate.
Now what? For decades, the car insurance industry has been built on brand marketing. The top three carriers spent $6 billion total in 2024 on marketing, betting that brand recognition correlates with consumer choice. But AI agents don't value sports sponsorships, arena logos or catchy jingles; they value the best price and coverage for each individual consumer.
For insurers, this transition means reallocating budgets and resources to pricing algorithms and models. It will directly affect three pillars of the insurance business: customer acquisition costs, retention and underwriting profitability. If carriers can't price risk accurately, that will be exposed immediately. APIs and easy integrations will be critical to make a seamless, fast experience for the AI agent. Carriers that rely on closed systems may face attempts at brute-force screen scraping, while those that build secure API doors for AI agents could maintain more control over their infrastructure and quoting costs.
As AI agents drive pure price shopping, the ultimate winners should be the carriers that can identify and price risk. Success in this new era doesn't just mean offering the lowest price for every driver. The strategic advantage will be advanced segmentation and pricing. Highly competitive rates that match individualized risk are critical. Side-by-side algorithmic comparisons will favor the carrier that prices risk most accurately. Pricing wins, and so does the customer.
The industry has seen major shifts before. First, customers could call to get quotes and bind policies, so they no longer needed to go into a brick-and-mortar office. Then the internet arrived, and insurers built simple web flows and new distribution networks to sell insurance. Mobile came next, making it easy to buy insurance via apps from anywhere. Today, customers don't even need to talk to anyone, a trend younger consumers avoid more and more. These advancements created a better customer experience.
AI agents are not a step in that direction; they are a giant leap.
In each era, some insurance companies won and some lost. The carriers that seized the moment were built for the transition and sprinted toward solutions; they didn't ignore, block or fight it. Modern tech stacks and a specialization in strategic partnerships that can create easy API integrations are table stakes.
Many have raised legitimate concerns regarding consumer protections, proper disclosure, transparency, misleading comparisons and the cost of automated quoting. Yes, those concerns are valid and should be addressed as the technology evolves. As in previous eras, customer habits will change, and protections should be modernized to match. These are important considerations, but they don't outweigh the technological advantages that deliver consumer benefits. The solution isn't blocking access.
The future is where price wins, where the best algorithm wins, and ultimately where the customer wins.
This material contains forward-looking statements within the meaning of federal securities laws; actual results may differ materially due to various risks and uncertainties outlined in our SEC filings.

